How National Organizations and Alumni Networks Protect Chapters
By Larry Betz | Prepared Not Paranoid https://www.preparednotparanoid.com/
Updated November 2, 2026
Fraternity insurance is something almost no parent asks about. Your student pays for it through their dues, but it often doesn't cover the very things most likely to go wrong. Here's how the money really works, and why it matters to your family.
A Quick Note on a Stat You'll See Everywhere
Before I get into this, you'll often see it claimed that fraternity men make up 85 percent of Fortune 500 CEOs. I looked for where that number actually comes from, and it traces back to fraternity organizations themselves, not an independent audit. It might be roughly true, it might be exaggerated. I genuinely can't verify it to a standard I'm comfortable handing you as fact, so take it as a commonly repeated claim rather than a confirmed statistic. What I can verify is much more specific, and honestly more useful, because it's about actual dollars and actual documented behavior rather than a talking point.
The Insurance System Built to Protect the Organization, Not the Members
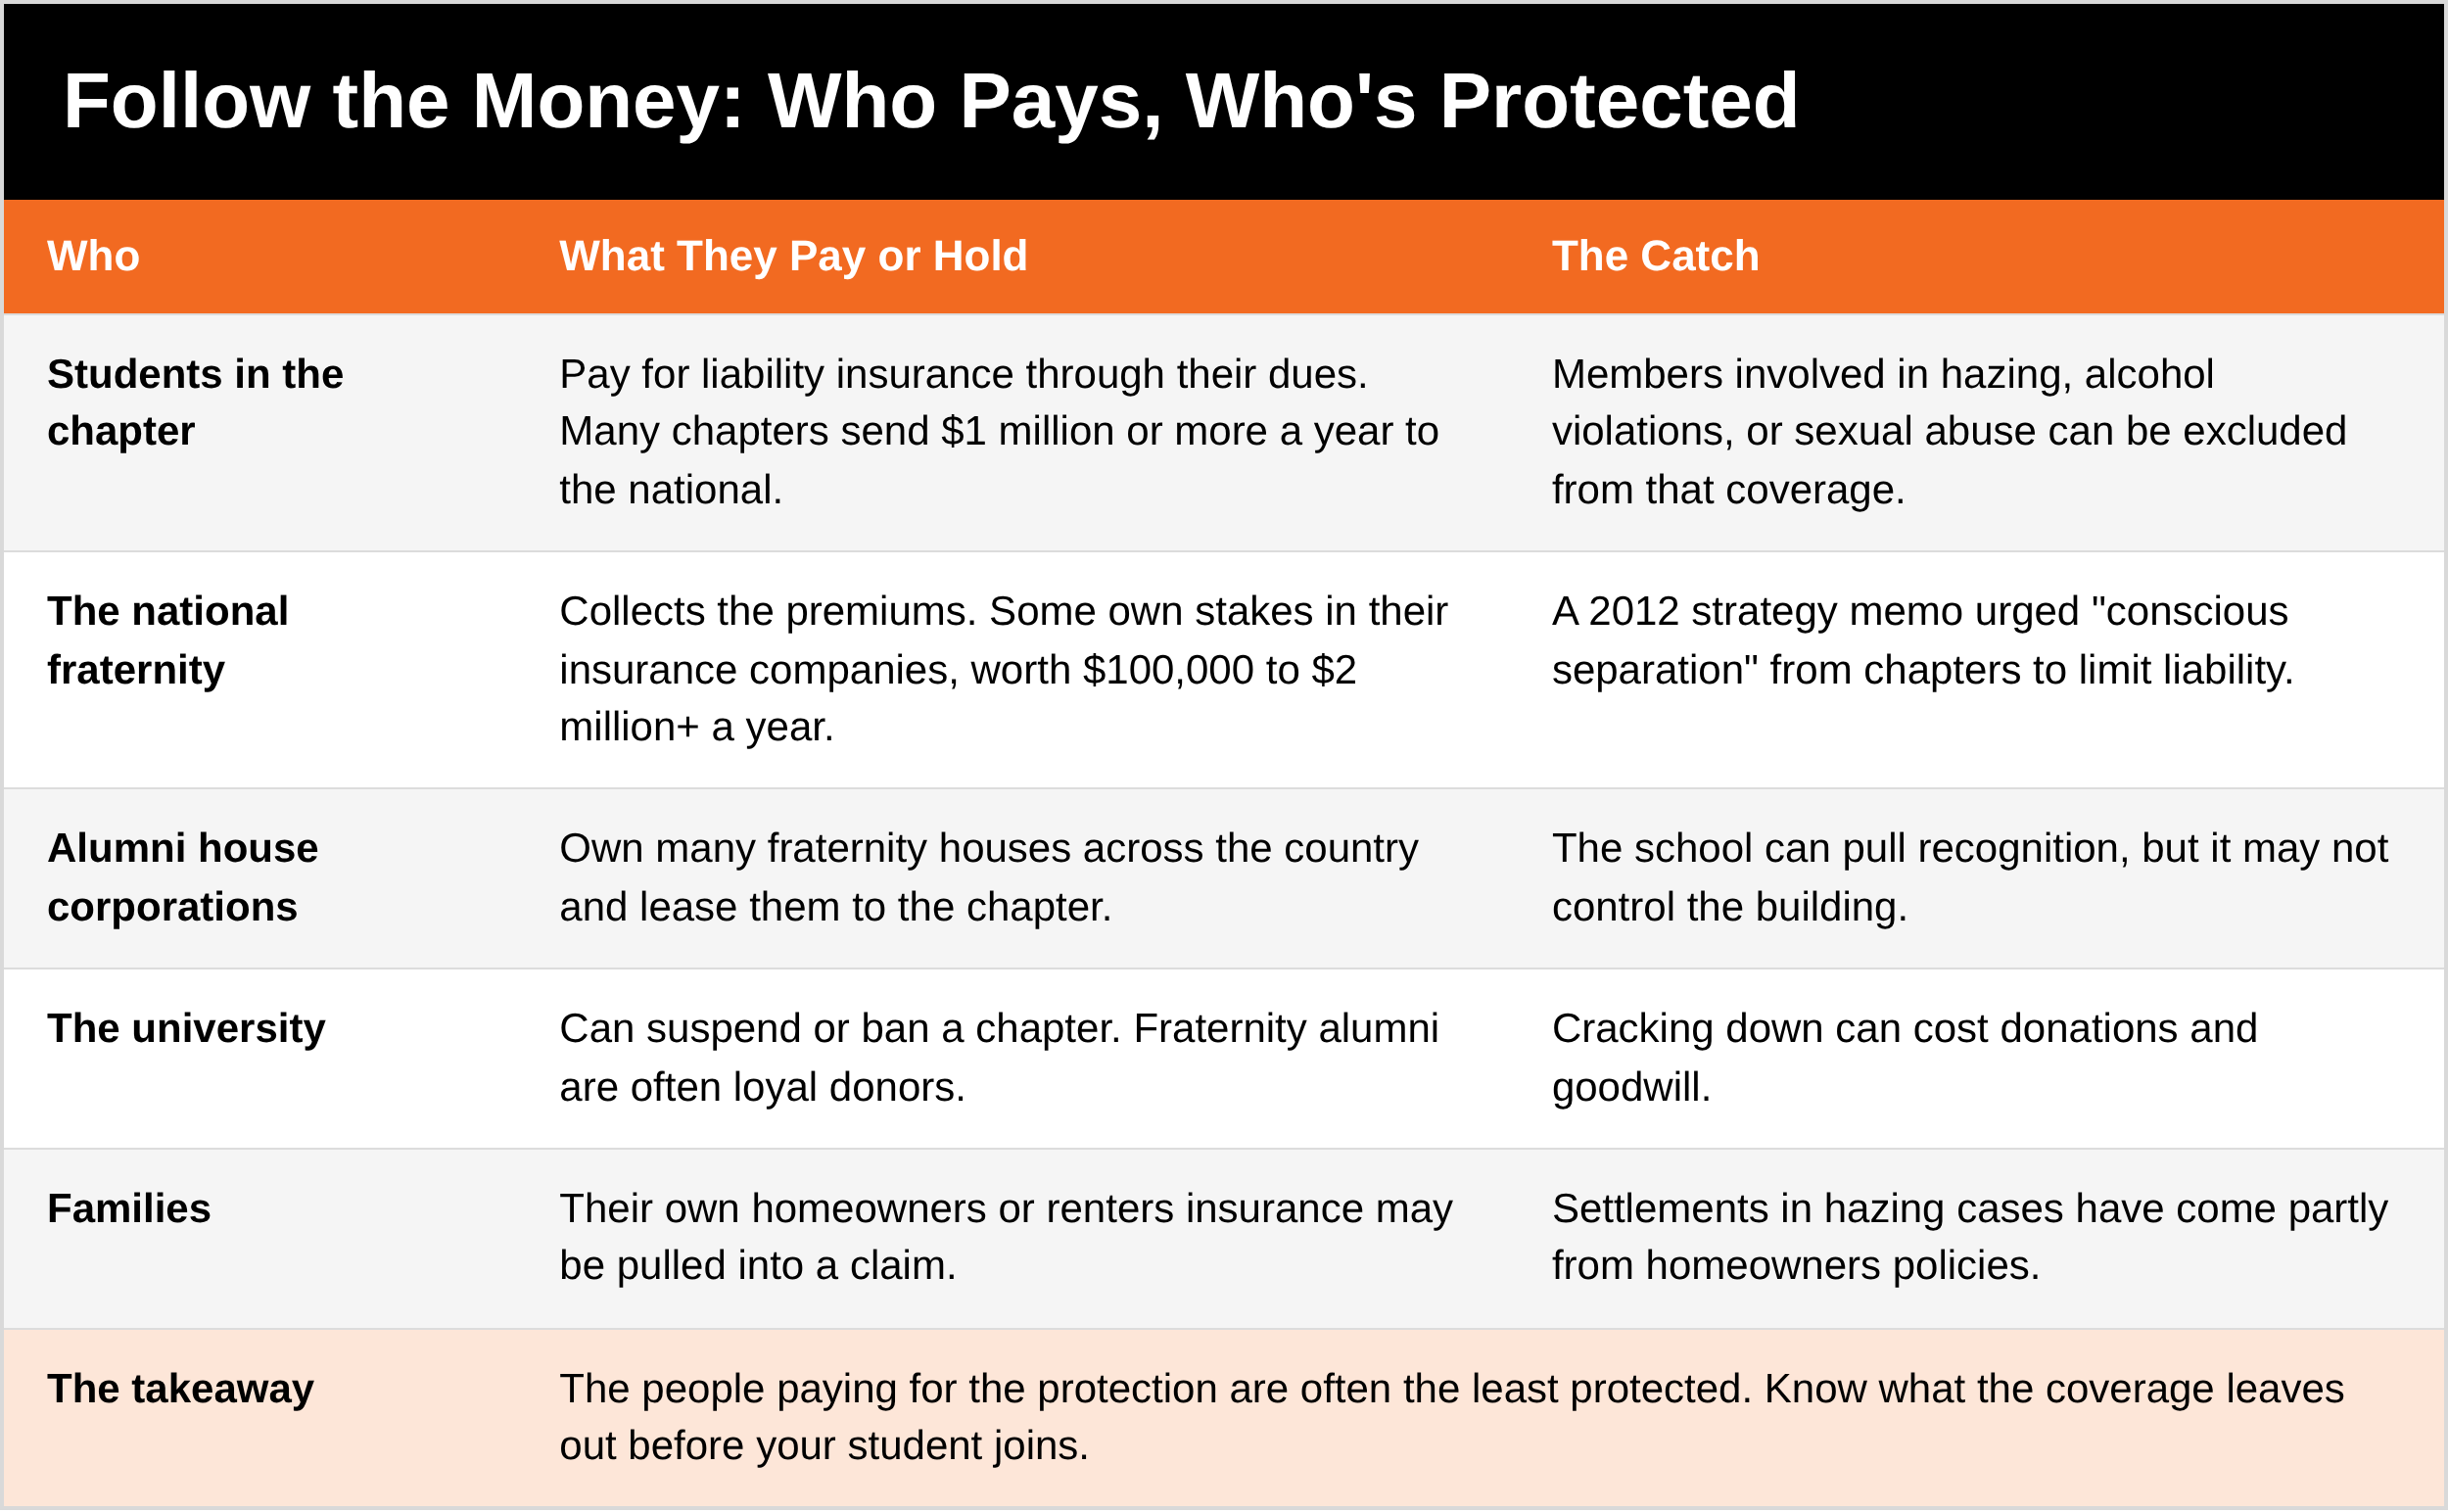
This is the part that surprised me most in researching this piece, and I think it'll surprise you too. National fraternities largely insure themselves, through insurance structures they created and often partly own. According to a 2023 investigation by InvestigateTV and Indiana University's Arnolt Center for Investigative Journalism, many chapters pay $1 million or more a year into the national organization's policy, through their members' dues, for liability coverage. Here's the catch: the national organizations' rules exclude from coverage any member involved in hazing, alcohol abuse, or sexual abuse, the exact behaviors everyone involved knows happen at chapters. Members are paying premiums for protection that may not cover them in the situations most likely to actually happen. A former fraternity executive who now testifies against fraternities in hazing cases called it "meaningless insurance."
The investigation uncovered a confidential 2012 strategy memo, presented at the annual meeting of the Fraternity Executives Association, that described this approach as "conscious separation." The guidance told national executives to stay deliberately distant from what happens at local chapters, on the logic that "more involvement = more potential liability." It also suggested creative settlement tactics, including using members' own homeowners insurance policies to, in the memo's words, "make the bad actor pay." In other words, an individual family's insurance, not the national fraternity's, absorbs the hit when something goes wrong.
The same investigation's review of federal tax records found one national fraternity holding nearly $20 million in assets built largely from those liability premiums, while ownership stakes in their insurance companies add anywhere from about $100,000 to more than $2 million a year.
Here's what that looks like for a real family. In 2018, Nicholas Mauricio, a member of Alpha Epsilon Pi at Florida State, was singled out by his own chapter as "Scumbag of the Week." As punishment, he was set up to take a slap to the face, and instead took a knockout punch that slammed his head onto a cement floor. He suffered a broken skull and bleeding on the brain. When his family's lawsuit settled, his mother was shocked to learn that some of the money came from homeowners insurance policies, not the national fraternity's liability coverage she assumed would pay.
Read that again slowly, because it's worth it. The organization set up to represent and protect a chapter's members financially benefits from those same members' dues, while structuring its own coverage to avoid paying out when the worst thing that's statistically likely to happen actually happens.
Here's who pays and who's protected.
Why Universities Are Reluctant to Push Back
The financial pressure runs the other direction too, from alumni onto the university itself. The Chronicle of Higher Education has reported that colleges have little motivation to crack down when Greek alumni are significant donors, and little legal responsibility for chapters living in private houses. One lawyer who advises colleges put the liability side bluntly in that same reporting: "The greater control you set up for Greek life, the more liability you assume." Schools and national organizations alike struggle to define who is responsible when things go wrong, and that confusion works in the chapter's favor.
Two real, named examples show what donor pressure looks like in practice. At Salisbury University in Maryland, after the school suspended its Sigma Alpha Epsilon chapter over hazing allegations in 2012, J. Michael Scarborough, an investment executive and one of the chapter's founding members, withdrew a $2 million donation. At Trinity College in Connecticut, after a student broke his neck diving into a shallow pool at a fraternity party, the president ordered fraternities and sororities to go coed. Alumni threatened to stop giving, and in May 2013 the president announced he would retire a year early. The college said the two weren't connected. Many alumni critics weren't so sure.
You'll also see a claim that 60 percent of 2013 donations over $100 million came from fraternity alumni. That figure comes from a 2015 Salon article that doesn't give a source, so I'd treat it as a talking point, not a fact. Here's one I can back up: a 2021 Gallup survey, reported by The Wall Street Journal, found that fraternity and sorority alumni donate to their schools at five times the rate of other graduates. At Cornell, about a third of undergraduates are in a fraternity or sorority. That puts a real number behind the incentive we're describing.
There's political money in this picture too. The Fraternity and Sorority Political Action Committee says it has raised more than $6.2 million over the past 20 years and contributed to hundreds of congressional candidates. Its 2026 annual dinner in Washington listed 2 sitting U.S. senators and 23 representatives as honorary hosts, each one a fraternity or sorority member. That's a direct line from Greek alumni networks into the same federal government that oversees higher education policy and funding.
To be fair, alumni giving isn't a bad thing on its own, and plenty of Greek alumni push their chapters to do better. The problem is when the money makes the people in charge hesitate.
Why This Actually Makes Discipline Harder, Structurally
There's also a practical, less conspiratorial piece of this worth understanding: who owns the house. Across the country, many fraternity houses are privately owned, usually by an alumni-run house corporation, a nonprofit set up by graduated members to hold title to the building and lease it back to the active chapter. That's a completely standard setup. On Cornell's own Edgemoor Lane, Lambda Chi Alpha's house is privately owned by its alumni corporation, for example.
Think through what that means for accountability. A university can suspend a chapter's official recognition, which is a real and meaningful consequence. It strips access to campus event registration, recruitment, and the school's own name and branding. What it can't always do, when it isn't the property owner, is lock the doors, control who has a key, or treat the building the way it would treat a dorm it owns. Campus police jurisdiction inside a privately owned house, which we covered fully in Part 4, is also a more complicated question than it is inside university housing. So a chapter can lose its recognition entirely and its house can, in practice, keep operating almost exactly as before, simply not as a university-sanctioned organization anymore. As one attorney who represents hazing victims put it to The Wall Street Journal, the university kicks them off campus, "and then they come back unchanged." On top of that, the house corporation holding the keys is usually run by alumni, the same population whose financial leverage over the university we just walked through.
But here's the twist in the Cornell case. The Chi Phi house at 107 Edgemoor Lane, where the alleged assault happened, isn't owned by an alumni corporation. According to Tompkins County property records, Cornell University is the listed owner. It's one of eight Cornell-owned fraternity houses, worth about $12.85 million combined, that pay no city, county, or school property taxes. After the case made national news, county lawmakers asked their attorney to review whether those exemptions should continue. The lawsuit itself argues that Cornell owned and controlled the house, and should have known what was happening inside it, including a drug-related police call there about a week before that night.
So ownership cuts both ways. When the school doesn't own the house, it has less control. When it does own the house, families have every right to ask why it wasn't watching more closely. Cornell has now shown it can act: in October 2026, it suspended all parties and social events at its Interfraternity Council houses for the rest of the school year.
Put all of it together and you get a system with layered incentives working against accountability at almost every level. The national organization is financially insulated from the worst outcomes by its own insurance design. The university is financially motivated to avoid alienating the alumni network that funds it. The physical property where a lot of this happens often sits outside standard university oversight, and even when it doesn't, oversight isn't guaranteed. None of that requires anyone to be acting in bad faith individually. It's simply what the structure rewards.
Where This Leaves Your Family
I'm not telling you this to say don't trust any of it. Plenty of chapters and plenty of alumni genuinely do the right thing. I'm telling you this so you understand that when something goes wrong inside a fraternity, the organizations with the most direct financial interest in the outcome, the national fraternity and the university's own development office, are not neutral parties. That doesn't mean either one is lying to you. It means their incentives aren't automatically aligned with full transparency, and knowing that going in is part of being a Prepared Protector rather than an uninformed one.
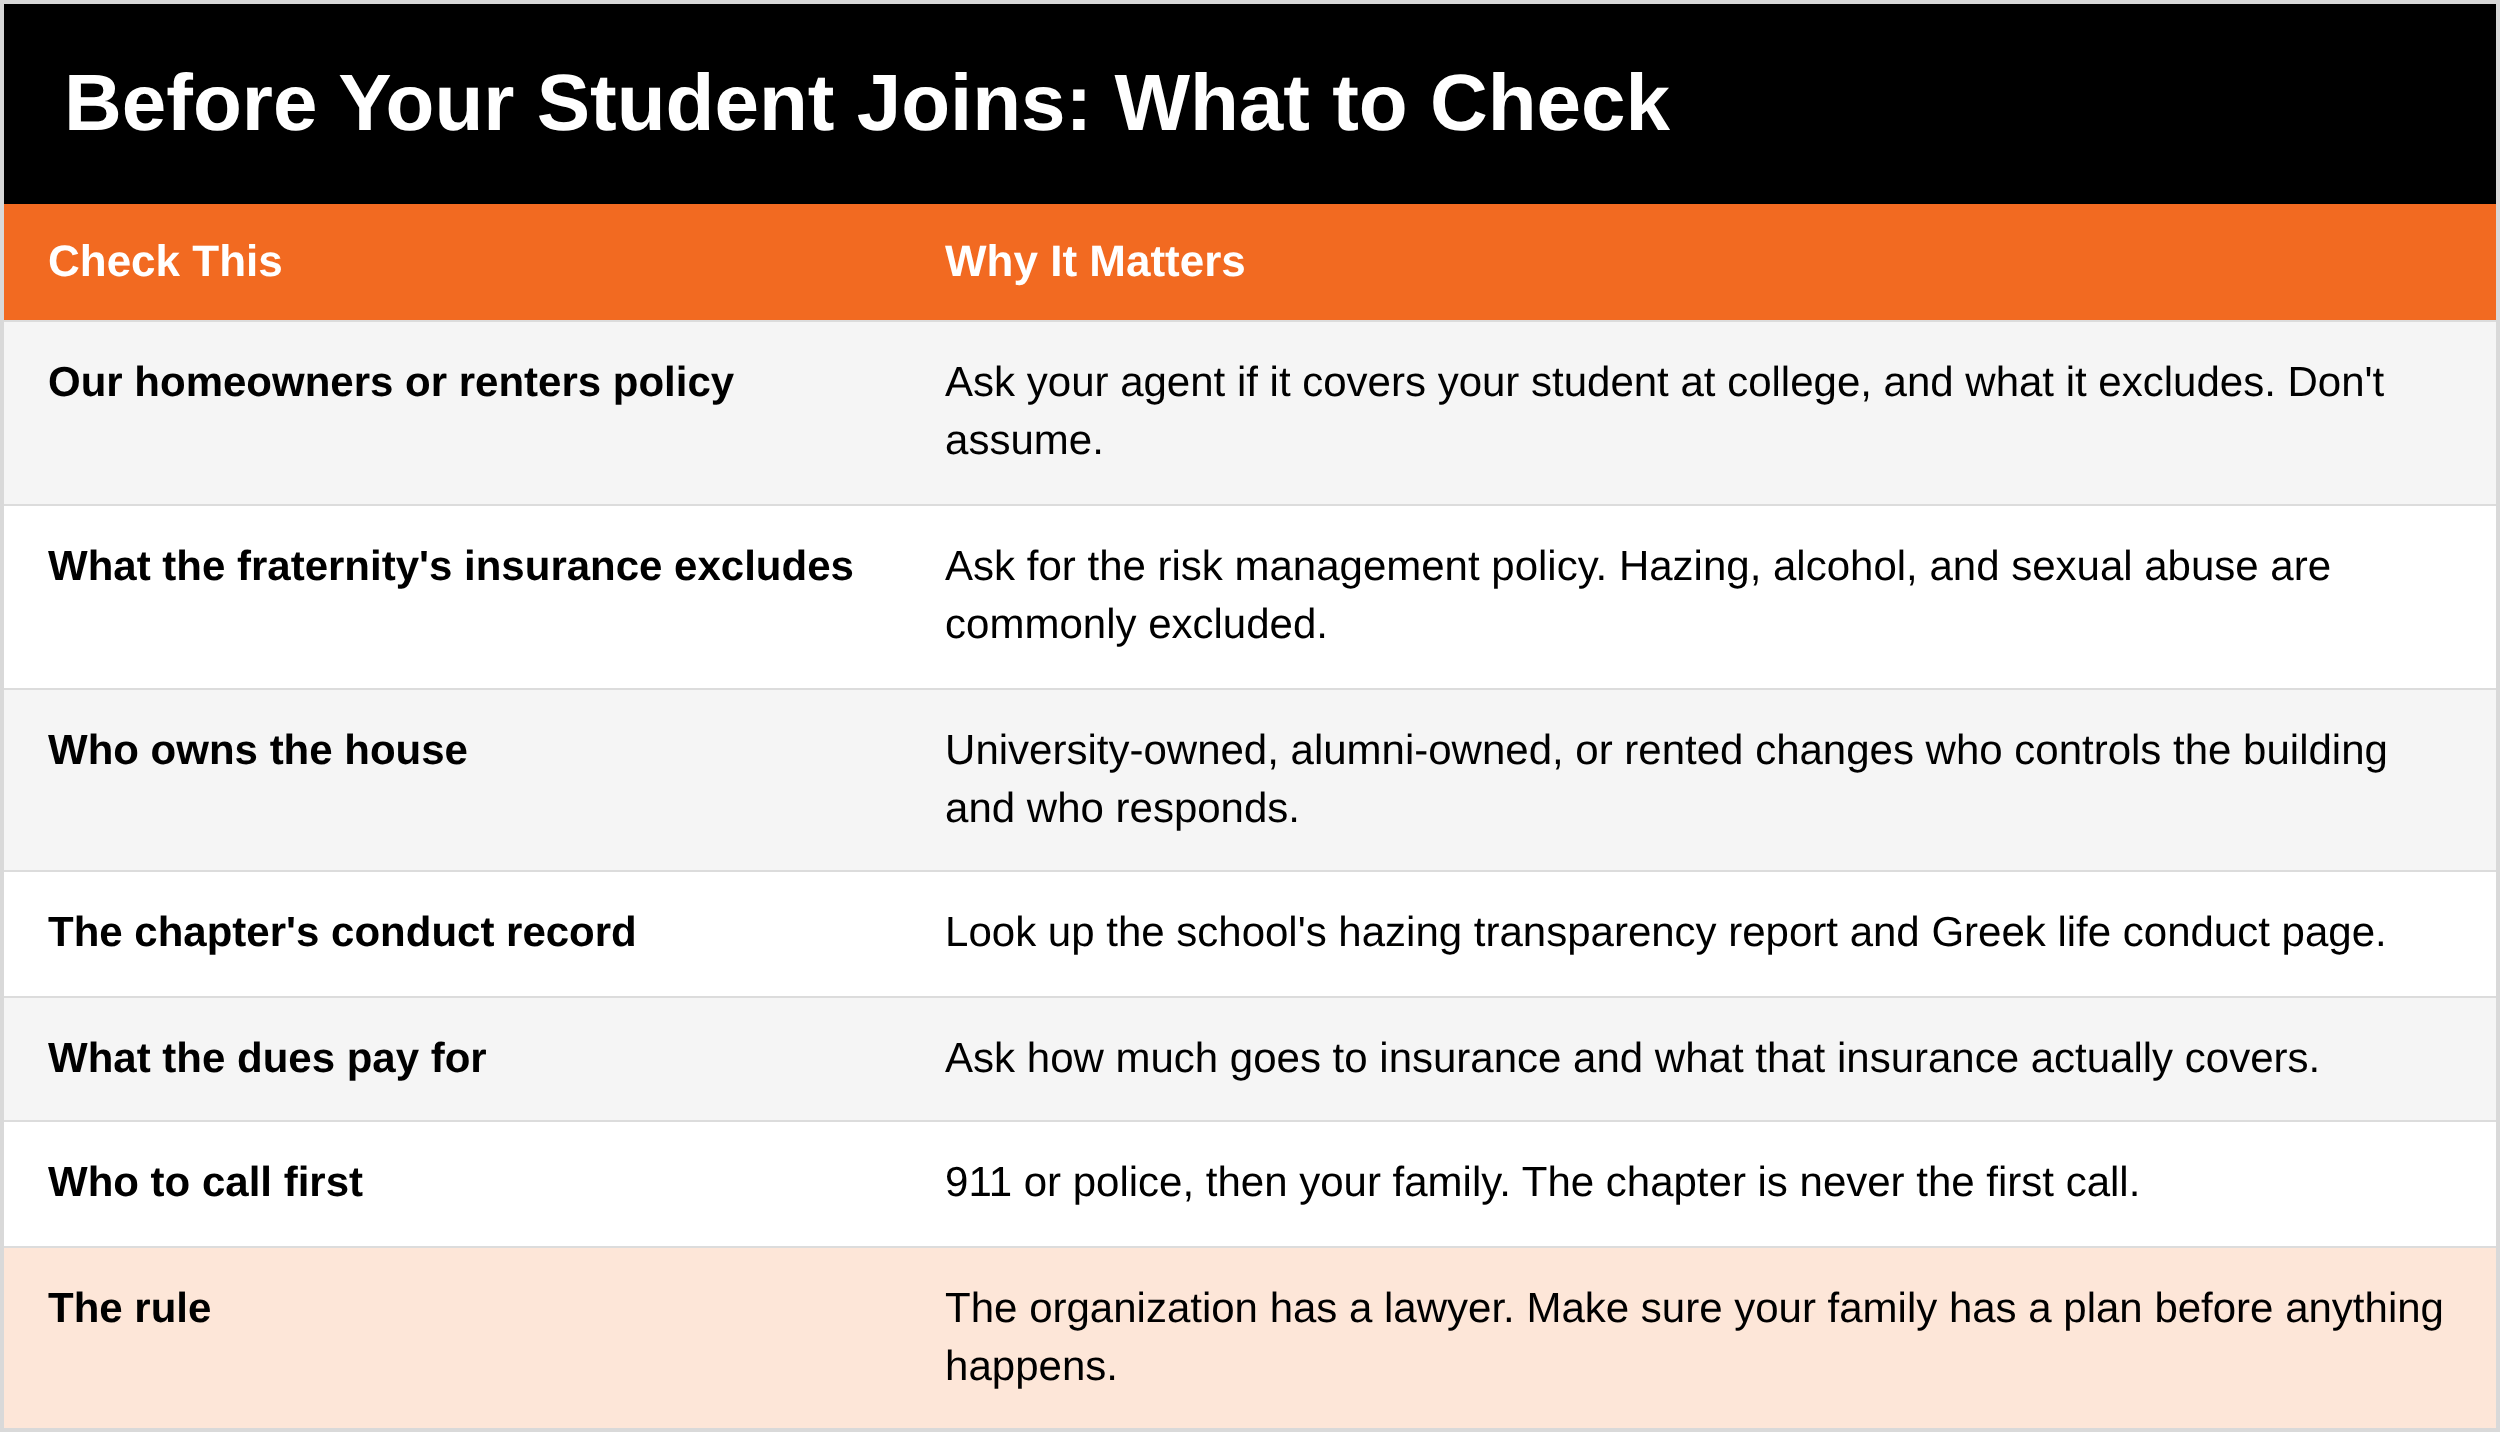
Here's what to check before your student joins.
The Prepared Protector Reads the Fine Print
The Prepared Protector doesn't assume someone else's insurance has their family covered. They call their own agent, ask the chapter what its coverage leaves out, and make sure their student knows the first call is never to the chapter. The organization has a plan for when things go wrong. Your family should have one too.
What to Say
Before your student joins
"Before you sign anything, let's find out what your dues actually pay for, and what the insurance doesn't cover."
"Who owns the house? Who's in charge if something goes wrong?"
About loyalty
"Loyalty to your brothers or sisters never means covering for something that hurts someone."
"If anything ever happens, it is never your fault. Call 911 or me first, not the chapter. I will help you first."
If something goes wrong
"Write down what happened, save the messages, and don't sign anything or give a statement to the chapter until we talk."
5 Quick Wins You Can Start Today
Call your insurance agent and ask whether your homeowners or renters policy covers your student at college, and what it excludes.
Ask the chapter for its risk management policy and what its insurance does not cover.
Find out who owns the house: the school, an alumni corporation, or a private landlord.
Look up the chapter on the school's hazing transparency report.
Read Conversations 2 and 19 in the free College Safety Conversation Guide together.
Ask Yourself
Do I know what my student's dues actually pay for?
Would my own insurance be pulled in if something happened at a chapter event?
Does my student know that the chapter is never the first call?
Remember
The national fraternity has lawyers, insurance, and a plan. Your family needs a plan too. Read the fine print, ask the hard questions, and make sure your student knows who to call first.
Get Started Today
Get the free College Safety Conversation Guide. It includes the conversations this post is built around, "Reporting, Silence, and Trust" and "Documentation and Reporting Options," with the actual words to start each one, plus the rest of the conversations every family should have before move-in day. DM the word [KEYWORD] on Instagram or Facebook and I'll send it to you. [Get it here: LINK]
Go Deeper
Navigating the Red Zone and Beyond. This post shows you how the money and the incentives work. The book shows your family how to stay safe in the situations where it matters most: party and drink safety, the Designated Steward and group plans, how manipulators use loyalty and pressure, boundary scripts, situational awareness with SCAN, how to support a friend, and what to do if the worst happens. [Get it here: https://link.amazon/B030JRBPp]
Tools I recommend: The dorm and party safety gear I recommend for your student's first year is in my College Dorm Room Essentials Amazon store. https://link.amazon/B061T3Evk
Related reading:
What's Happening on Campus, Part 3: It's One Big Club [LINK]
What's Happening on Campus, Part 4: Who Campus Police Actually Work For [LINK]
What's Happening on Campus, Part 6: What the Research Actually Shows About Greek Life [LINK]
College Safety Resource Center [LINK]
References
InvestigateTV and the Arnolt Center for Investigative Journalism. Hazed and Excused: Some national fraternities shift financial responsibility in hazing deaths through self-created insurance system. August 21, 2023. https://www.ky3.com/2023/08/21/hazed-excused-some-national-fraternities-shift-financial-responsibility-hazing-deaths-through-self-created-insurance-system/
Kelderman, E. Why Colleges Don't Do More to Rein In Frats. The Chronicle of Higher Education, March 27, 2015. https://www.chronicle.com/article/why-colleges-dont-do-more-to-rein-in-frats/
McDonough, K. How racist frat boys get away with it: Big money and the real Sigma Alpha Epsilon scandal. Salon, March 12, 2015. https://www.salon.com/2015/03/12/what_scares_university_presidents_more_angry_donors_or_racists_and_rapists_on_campus
Inside Higher Ed. News brief on Trinity College President James Jones announcing his early retirement, May 2013. https://insidehighered.com/node/37972
The Wall Street Journal. A Long History of Reining In Fraternities at Cornell Has Come Up Short. October 16, 2026.
Fraternity and Sorority Political Action Committee. Kicking Off a Year of Celebration, January 2025, and 2026 Annual Dinner Congressional Honorary Hosts. https://fspac.org/
CNY Central. Eight Cornell-owned frat properties worth $12.85M listed as fully exempt from taxes. October 2026. https://newschannel9.com/news/nation-world/tompkins-county-reviews-tax-exemptions-for-cornell-fraternity-houses
Finger Lakes 1. Lawsuit accuses Cornell, Greek organizations and students in alleged 2024 sexual assault. September 21, 2026. https://www.fingerlakes1.com/2026/09/21/lawsuit-accuses-cornell-greek-organizations-and-students-in-alleged-2024-sexual-assault/
WBNG. Cornell University, fraternity sued by former student after alleged gang rape and drugging in 2024. September 2026.
Higher Ed Dive. Numerous factors work against institutions regulating frats. March 2015. https://www.highereddive.com/news/numerous-factors-work-against-institutions-regulating-frats/380748/
Betz, L. Navigating the Red Zone and Beyond.
Disclaimer
This article is for general informational and educational purposes only and is meant to start conversations in your family. It is not legal, financial, or insurance advice. Insurance policies and laws vary, so talk with your own insurance agent and an attorney about your family's coverage, and check your state and county for the exact laws where your student lives and goes to school. No one named in the Cornell case has been charged with a crime as of this update, and the claims in the civil lawsuit have not been proven in court. If you suspect abuse, assault, or hazing, contact a professional or law enforcement immediately. Prepared Not Paranoid and Larry Betz are not responsible for the content of third-party websites or resources linked here. Affiliate disclosure: I've linked to products from my Amazon store that I personally recommend. As an Amazon Associate, I earn from qualifying purchases, at no extra cost to you. Thank you for supporting my work.
If you or someone you love is in danger, call 911. For confidential support after a sexual assault, call the National Sexual Assault Hotline at 800-656-4673 (800-656-HOPE), any time, day or night.
Awareness gives you time. Time gives you options.
The Prepared Protector is someone who's decided that loving someone means being ready for them, not just hoping things go fine.
Prepared Not Paranoid. Protecting the Most Vulnerable Among Us.